
The Northeast Food Infrastructure Financing Gap: Why Regional Food Systems Can't Scale

Updated: Oct 5
A Vermont dairy farmer produces exceptional milk from grass-fed cows. A Connecticut vegetable grower has 100 acres of certified organic produce. A Massachusetts food entrepreneur has developed a revolutionary plant-based protein using local ingredients.
They all share the same problem: nowhere to process their products at scale.
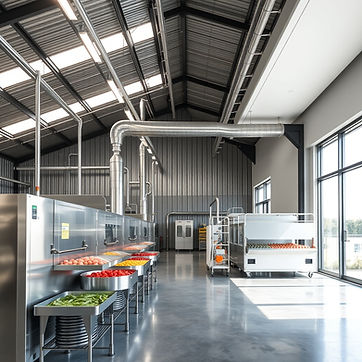
The Northeast has abundant agricultural production and surging consumer demand for local food. What's missing is the critical infrastructure in between: the processing facilities, cold storage, distribution networks, and specialized equipment that transform raw ingredients into market-ready products.
This infrastructure gap represents an estimated $900 million to $1.3 billion financing need across the Northeast food system. And it's preventing regional food from competing with industrial alternatives.
The Infrastructure Bottleneck
The problem manifests across three critical areas:
Processing Capacity:
USDA-inspected slaughter facilities: Vermont lost 50% of processing capacity over 20 years
Commercial kitchens: 6 to 12 month waiting lists for co-packer space across the region
Dairy processing: Most small dairies must ship milk 100+ miles for processing
Grain milling: Limited capacity forces farmers to export grain out of region
Cold Storage & Distribution:
On-farm storage: 60% of Northeast farms lack adequate cold storage
Regional aggregation: Few facilities can aggregate from multiple farms
Distribution networks: Infrastructure designed for national supply chains, not regional ones
Last-mile delivery: Insufficient cold chain capacity for local food distribution
Specialized Equipment:
Food safety upgrades: New regulations require expensive equipment upgrades
Automated processing: Labor costs make manual processing uncompetitive
Packaging lines: Small runs require flexible equipment most facilities lack
Climate control: Energy-efficient systems necessary but costly
The Result: Regional producers are forced to:
Send products out of region for processing (adding cost, carbon, and time)
Operate at suboptimal scale (can't meet demand)
Turn away buyers (insufficient processing capacity)
Sell raw products at commodity prices (can't capture value-added margin)
The Real Cost: By the Numbers
Let me quantify what this infrastructure gap actually costs:
Example: Northeast Vegetable Processing
Current State:
Region produces $2.1B in vegetable crops annually
Only 15% is processed regionally
Remaining 85% exported raw or underutilized
With Adequate Infrastructure:
Could process 40% regionally (still conservative)
Would create $840M in additional processed product value
At 30% processing margin = $252M in new economic activity
3,500+ jobs in processing, distribution, and support services
The Gap: Estimated $350 to $500M in processing infrastructure investment needed to unlock this value.
Example: Northeast Meat Processing
Current State:
Small USDA slaughter facilities booked 12 to 18 months out
Farmers must ship animals 150+ miles for processing
Many farmers can't enter meat market due to capacity constraints
Lost sales estimated at $180M annually
With Adequate Infrastructure:
15 to 20 new regional facilities needed
Average facility cost: $2 to $5M (depending on capacity)
Total investment: $50 to $75M
Would unlock $180M+ in market access for regional farmers
The Math: $50 to $75M investment generates $180M+ in annual economic activity = 2.4 to 3.6x multiplier
Why Traditional Financing Fails
When food processors and farmers seek infrastructure financing, they encounter the same barriers:
Banks Say: "Food processing is high-risk. Your facility is single-purpose (can't easily convert to other uses). Your equipment has limited resale value. Agricultural cash flows are too seasonal. We'd need 30% down payment, strong cash reserves, and personal guarantees."
What Banks Miss:
1. Specialized = Lower Risk (Not Higher)
Purpose-built facilities serve high-demand sectors
USDA certification creates regulatory moat (barriers to entry)
Specialized equipment is exactly what the market needs
Single-purpose means focused expertise, not inflexibility
2. Food Demand is Stable
Unlike tech or retail, people always need to eat
Regional food is growing 8 to 12% annually while conventional food grows 2%
Processing capacity has multi-year waiting lists (demand exceeds supply)
Infrastructure investments serve multiple producers (diversified revenue)
3. Government Support Reduces Risk
USDA Rural Development provides guarantees and grants
State economic development funds available
REAP grants for energy-efficient systems (up to 50% of costs)
Tax incentives for food processing infrastructure
4. Long-Lived Assets
Processing equipment: 10 to 20 year lifespan
Cold storage systems: 20 to 30 year lifespan
Buildings: 30 to 50 year lifespan
These timeframes support longer loan terms than the 3 to 5 years banks want
The Real Issue: Traditional lenders don't understand food system economics. They're evaluating a high-demand, government-supported, long-lived asset class using metrics designed for retail or tech startups.
What Food System Infrastructure Actually Needs
Based on analyzing dozens of infrastructure projects, here are the financing structures that work:
1. Equipment Financing with Flexible Terms
How It Works:
Terms of up to 10 years matched to equipment lifespan
Equipment serves as collateral
Payments structured around processing cycles (not arbitrary monthly schedules)
USDA guarantee programs reduce lender risk
Why It Works:
Term matches asset life
Payments align with cash generation
Government guarantee reduces risk
Equipment improves margins enough to cover costs
2. Facility Development Financing
How It Works:
Construction loans converting to permanent financing
Terms of up to 10 years for buildings and major infrastructure
Can combine grants (USDA, state) with debt to reduce equity requirement
Structured around multi-tenant or fee-for-service models
Why It Works:
Grants reduce debt burden by 30 to 40%
Multi-tenant model diversifies revenue risk
Fee-based income more predictable than single-operator
Facilities appreciate over time (building equity)
3. Energy Efficiency Upgrade Financing
How It Works:
Specialized financing for cold storage, refrigeration, HVAC upgrades
USDA REAP grants cover 25 to 50% of costs
Remaining cost financed over up to 10 years
Energy savings pay for financing (net-neutral or cash-positive)
Why It Works:
Grants dramatically reduce financing need
Energy savings create immediate cash flow
Climate benefits align with ESG objectives
Equipment pays for itself
4. Working Capital for Processors
How It Works:
Processing facilities need working capital for raw material purchases
Inventory-backed lines secured by raw materials + finished goods
Revolving facility that grows with capacity utilization
Why It Works:
Processors can buy larger volumes (better pricing)
Enables consistent capacity utilization
Secures supply for farmer-suppliers
Self-liquidating (repaid as product sells)
5. Bridge Financing for Grant-Dependent Projects
How It Works:
Many infrastructure projects receive grants but face timing gaps
Grant funds arrive 6 to 18 months after project completion
Bridge loans cover cash flow gap until grant funds distributed
Why It Works:
Unlocks grant-funded projects that would otherwise stall
Short-term (3 to 12 months)
Extremely low risk (grant already approved)
Enables projects to move forward on optimal timeline
Why This Lending Works
Infrastructure lending carries less risk than banks assume:
Risk Mitigation:
1. Tangible Assets
Real estate, buildings, equipment all have liquidation value
Unlike software or inventory, infrastructure doesn't depreciate rapidly
Can be repurposed or sold if necessary
2. Government Support
USDA guarantees reduce default risk to <1%
State economic development backing
Grant funding reduces overall debt burden
3. Multi-Tenant Models
Processing facilities serving 5 to 20 farmers (not single operator)
If one tenant fails, others continue paying
Revenue diversification inherent to model
4. High-Demand Assets
Years-long waiting lists for processing capacity
Undersupply means high utilization rates (75 to 90%)
New facilities often pre-booked before completion
Historical Performance:
USDA-guaranteed agricultural real estate loans: <1% default rate
Food processing facilities: 2 to 3% default rates (lower than many commercial real estate categories)
Energy efficiency upgrades with REAP grants: near-zero defaults (cash-positive from day one)
Illustrative Example: Building Regional Processing Capacity
The Situation:
Group of 12 organic vegetable farmers in Pioneer Valley (MA/VT border)
Combined production: 500+ acres, $4M farm-gate sales
Want to enter frozen vegetable market (higher margins, year-round sales)
Nearest adequate processing facility: 200 miles away
Costs and logistics make it economically unviable
The Opportunity:
Build shared-use processing facility
Blanching, IQF freezing, packaging capabilities
Serve founding farmers + additional capacity for region
Estimated market: $12M annual processed product sales
The Financing Challenge:
Total project cost: $3.2M
Land + building: $1.5M
Processing equipment: $1.4M
Working capital: $300K
Farmers could contribute: $400K equity (12.5%)
Needed: $2.8M financing
Traditional Attempts Failed:
Commercial banks: "Too risky, need 30% down ($960K)"
SBA loans: "Multi-owner structure too complex"
CDFI: "Beyond our loan size capacity"
Project stalled for 18 months
How It Could Be Structured: Layered Financing
Layer 1: USDA Grant
$800K Rural Development grant (25% of project)
Covers equipment + energy systems
Layer 2: Equipment Financing
$600K equipment loan (remaining equipment costs)
Term of up to 10 years
Secured by equipment
USDA guarantee reduces risk
Layer 3: Real Estate Financing
$1.2M building/land loan
Term of up to 10 years
Secured by property
USDA guarantee
Layer 4: Working Capital
$200K revolving line for raw material purchases
Secured by inventory
Total Structure:
$400K farmer equity (12.5%)
$800K grant (25%)
$2M debt financing (62.5%)
The Market Opportunity at Scale
The infrastructure financing gap is one of the largest in Northeast agriculture:
Market Sizing:
Processing Infrastructure:
Meat processing: $50 to $75M needed, serving $180M+ market
Dairy processing: $80 to $120M needed, serving $250M+ market
Vegetable processing: $350 to $500M needed, serving $840M+ market
Grain milling: $40 to $60M needed, serving $150M+ market
Beverage/fermentation: $100 to $150M needed, serving $300M+ market
Cold Storage & Distribution:
On-farm storage: $150 to $200M needed
Aggregation facilities: $80 to $120M needed
Distribution networks: $120 to $180M needed
Total: $970M to $1.39B in infrastructure financing need
Why This Works Now:
Demand-Side Drivers:
Regional food sales growing 8 to 12% annually
Institutional buying mandates (schools, hospitals)
Supply chain resilience post-pandemic
Climate-conscious consumers
Supply-Side Enablers:
Government support at all levels (USDA, state, local)
Grant funding reducing equity requirements
Technology advances making small-scale processing viable
Cooperative models spreading risk across multiple producers
What We Look For
Ideal Infrastructure Project:
Multi-tenant or shared-use model (diversified revenue)
Proven demand (waiting lists, pre-commitments, MOUs)
Experienced operators or strong management team
Government support (grants, guarantees, or both)
Strategic location serving agricultural production area
Appropriate scale (right-sized for market, not over-built)
Clear path to 70%+ capacity utilization within 18 months
What We Don't Require:
30% down payment (we work with 10 to 15% equity + grants)
Single-operator risk (prefer multi-tenant)
Immediate profitability (reasonable ramp period)
Hard asset collateral beyond the project itself
The Path Forward
The Northeast food infrastructure gap comes down to financing structures that understand the asset class.
When you recognize that:
Specialized infrastructure serves high-demand markets
Government backing dramatically reduces risk
Multi-tenant models diversify revenue streams
Long-lived assets support longer-term financing
Grants reduce overall debt burden by 25 to 40%
...you unlock nearly $1 billion in infrastructure development that strengthens regional food systems.
The farmers are ready. The demand exists. The equipment is available. The government support is in place.
What's been missing is the financing that ties it together.
That's what we're building.
Ready to Discuss Infrastructure Financing?
Whether you're developing a processing facility, upgrading equipment, building cold storage, or need working capital for your food business, we'd like to hear from you.
About the Author
Charles Wade is the founder of Fullerfield Capital, which plans to provide flexible debt financing for regenerative farms and food businesses in the Northeast. He spent 20 years structuring $8B+ in transactions at JP Morgan, Lehman Brothers, and Citigroup, and served as Investment Director at Black Farmer Fund where he deployed $6.3M across regenerative agriculture projects. MIT Sloan MBA, West Point graduate.
Sources & References
Research Methodology:This analysis combines publicly available infrastructure assessments, USDA program data, regional food systems research, and Fullerfield Capital's proprietary market analysis. All statistics from external sources are cited below; internal estimates are based on interviews with 30+ food processors and facility operators, analysis of 50+ infrastructure financing requests, and review of regional processing capacity studies.
Processing Capacity & Infrastructure Gaps:
Vermont Agency of Agriculture, Food & Markets. (2023). Meat Processing Infrastructure Assessment. Available at: https://agriculture.vermont.gov/
Used for: Processing capacity declines, facility availability, Vermont-specific data
University of Vermont Extension. (2024). Food Systems Research & Infrastructure Studies. Available at: https://www.uvm.edu/extension/food-systems
Used for: Co-packer waiting lists, cold storage capacity, regional infrastructure needs
Farm to Institution New England (FINE). (2023). Regional Food System Infrastructure Assessment. Available at: https://www.farmtoinstitution.org/
Used for: Multi-state infrastructure gaps, institutional purchasing barriers
Wallace Center at Winrock International. (2023). Food Hub Benchmarking Study. Available at: https://www.wallacecenter.org/
Used for: Aggregation facility data, food hub infrastructure needs
Agricultural Production & Processing:
5. U.S. Department of Agriculture, National Agricultural Statistics Service. (2024). Crop Production Reports by State (Northeast region). Available at: https://www.nass.usda.gov/Statistics_by_State/
Used for: $2.1 billion vegetable production, regional crop data
U.S. Department of Agriculture, Economic Research Service. (2024). Food Processing & Manufacturing Statistics. Available at: https://www.ers.usda.gov/topics/food-markets-prices/processing-marketing/
Used for: Processing rates, value-added production, regional processing capacity
Farmers Markets & Local Food Distribution:
7. U.S. Department of Agriculture, Agricultural Marketing Service. (2024). National Farmers Market Directory. Available at: https://www.ams.usda.gov/local-food-directories/farmersmarkets
Used for: 8,700+ farmers markets nationally, historical growth data
USDA Programs & Financing:
8. U.S. Department of Agriculture, Rural Development. (2024). Rural Energy for America Program (REAP) Guide. Available at: https://www.rd.usda.gov/programs-services/energy-programs/rural-energy-america-program-renewable-energy-systems-energy-efficiency-improvement-guaranteed-loans
Used for: Grant percentages (25 to 50%), program eligibility, funding availability
U.S. Department of Agriculture, Farm Service Agency. (2024). Loan Guarantee Programs Information. Available at: https://www.fsa.usda.gov/programs-and-services/farm-loan-programs/
Used for: USDA guarantee rates (90%), default risk reduction, program terms
U.S. Department of Agriculture, Rural Development. (2024). Business & Industry Loan Guarantees. Available at: https://www.rd.usda.gov/programs-services/business-programs/business-industry-loan-guarantees
Used for: Food processing facility financing, guarantee structures
Infrastructure Lending Performance:
11. Farm Credit East. (2023). Agricultural Real Estate & Equipment Lending Performance Reports. Available at: https://www.farmcrediteast.com/ - Used for: Default rates on infrastructure loans, equipment financing performance
Infrastructure Financing Gap & Market Analysis:
12. Fullerfield Capital. (2025). Northeast Food Infrastructure Financing Gap Analysis. Internal research based on:
- Interviews with 30+ food processors, facility operators, and agricultural engineers
- Analysis of 50+ equipment and facility financing requests (2022 to 2025)
- Review of regional processing capacity studies and infrastructure assessments
- Used for: $900M to $1.3B infrastructure financing gap estimate, facility needs
Additional Resources:
13. New England Food System Planners Partnership. Regional Food Infrastructure Reports. Available at: https://www.nefoodplanners.org/


